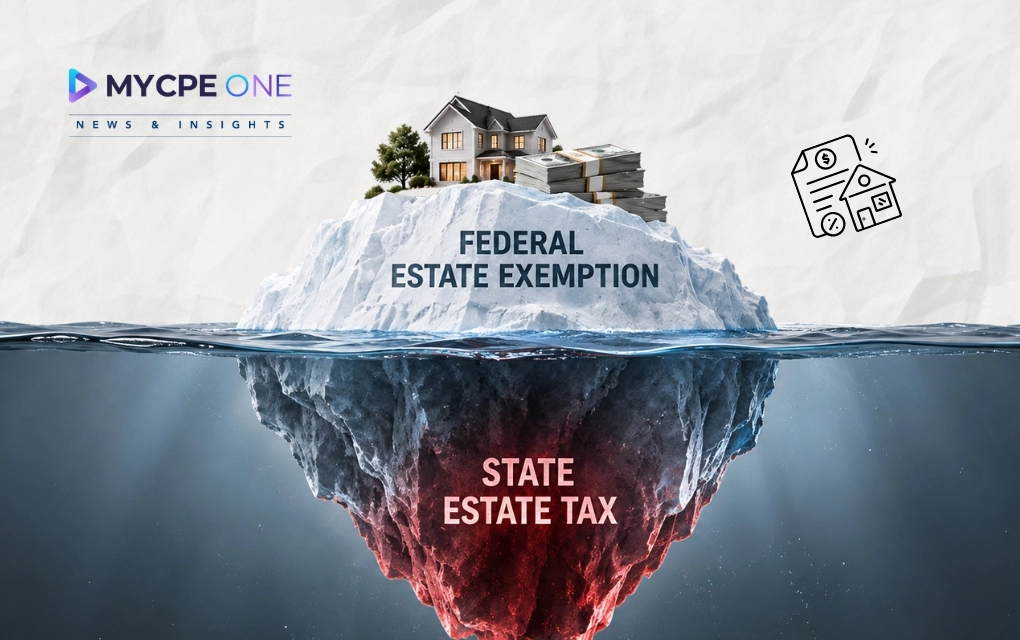
The article discusses the potential complexities and financial implications for estates due to differing federal and state estate tax rules, particularly the disconnect arising as states like Oregon, Massachusetts, and New York maintain lower taxation thresholds compared to the $15 million federal estate tax exemption set for 2026. This matters because it underscores the need for individuals and advisors to carefully consider state-specific estate planning to prevent unexpected tax liabilities, as reliance on federal exemptions alone can lead to costly misunderstandings regarding estate tax obligations.
A $15 million estate tax exemption sounds like a pretty comfortable cushion. For a married couple, federal portability can potentially push that protection much higher. So a client worth $4 million, $7 million, or even $10 million may reasonably think est...
Subscribe now for $189 and get unlimited access to MYCPE ONE, from CPE credits to insights Magazine
📢MYCPE ONE Insights has a newsletter on LinkedIn as well! If you want the sharpest analysis of all accounting and finance news without the jargon, Insights is the place to be! Click Here to Join
Unlock Annual Access to News & CPE Subscription
You’ve reached the 3 free-content piece limit. Unlock unlimited access to all News & CPE resources. Subscribe Today.
Experience MYCPE ONE at its best! Upgrade your browser for a more interactive, user-friendly interface, and stay ahead in your professional development journey.